GST Input Tax Credit (ITC) 2026: How to Avoid Common Mistakes
Input Tax Credit (ITC) is one of the most important parts of GST compliance. Eligible businesses can generally claim credit of GST paid on qualifying purchases and use it against their output GST liability, subject to applicable conditions, restrictions and documentation requirements.
However, simply recording a purchase invoice in the books does not automatically mean that ITC can be claimed. Businesses should regularly reconcile their purchase register, invoices and GST data before filing returns.
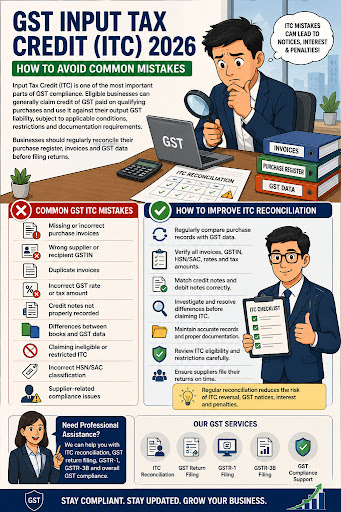
Common GST ITC Mistakes
Businesses should watch for:
- Missing or incorrect purchase invoices
- Wrong supplier or recipient GSTIN
- Duplicate invoices
- Incorrect GST rate or tax amount
- Credit notes not properly recorded
- Differences between books and GST data
- Claiming ineligible or restricted ITC
- Incorrect HSN/SAC classification
- Supplier-related compliance issues
How to Improve ITC Reconciliation
Regular reconciliation can help identify discrepancies before they become major compliance issues. Businesses should compare purchase records with the relevant GST data, verify invoices and investigate differences before claiming ITC.
Maintaining accurate records and reviewing ITC regularly can help reduce the risk of ITC reversal, GST notices, interest and penalties.
If you need professional assistance, we can help with ITC reconciliation, GST return filing, GSTR-1, GSTR-3B and overall GST compliance.